
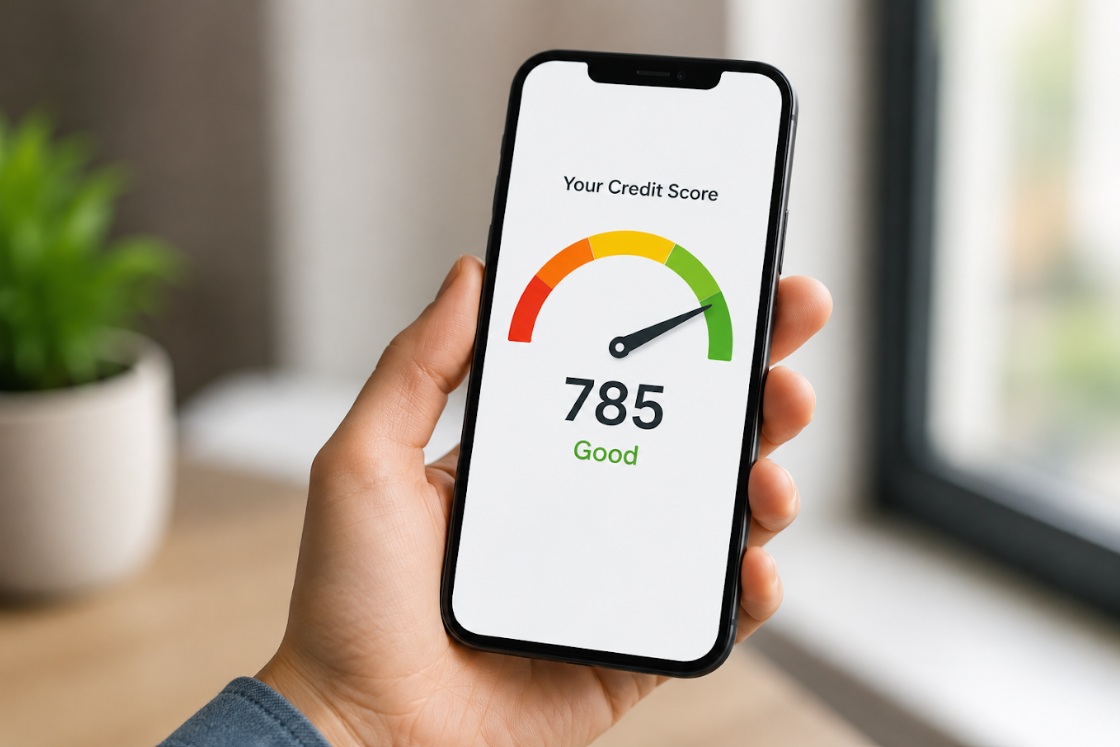
A credit score provides a quick view of an individual’s credit standingHowever, understanding credit health involves looking beyond the score and reviewing the credit information behind it.
 |
Check Credit Score and Understand Credit Health with the Bajaj Finance Credit Pulse Report
The Bajaj Finance Credit Pulse Report provides an online way to check available credit information at no additional costReviewing this information can help individuals understand their credit profile, stay aware of their credit position and make informed decisions about future borrowing.
What is a credit score?
A credit score is a numerical representation of information in an individual’s credit historyIt provides a quick view of credit standing and forms one part of the overall credit profile.
The score is calculated using information related to an individual’s credit behaviourFactors such as payment history, credit utilisation, credit history and credit accounts can contribute to credit scoring.
A credit score is therefore useful as a starting point, but it does not provide the complete context of an individual’s credit profile.
How to check a credit score online?
A credit score can be checked through different online channels, including credit bureau websites and financial platforms that provide access to credit informationThe process usually involves entering basic personal details and completing a verification step before the available credit information can be accessed.
The Bajaj Finance Credit Pulse Report provides an online way to check available credit information.
Step 1: Visit the Bajaj Finance Credit Pulse Report page
Individuals can visit the official Bajaj Finance website and open the Bajaj Finance Credit Pulse Report pageThe option to check the credit score can then be selected.
Step 2: Verify the registered mobile number
The registered mobile number needs to be enteredAn OTP is sent to the number to complete the verification process.
Step 3: Enter the required details
Customers need to provide details such as their name, PAN, date of birth, email address, mobile number and PIN code.
Step 4: Access the credit score
Once the required verification is completed, the available credit score is displayed on the screen.
Step 5: Review the credit report
The available credit information can then be reviewed to understand the credit profileThe report includes information relating to repayment history, credit accounts, recent enquiries and other credit-related details.
The report can also be downloaded for future reference.
What is credit health?
Credit health refers to the broader condition of an individual’s credit profile and how credit has been managed over time.
A credit score is one part of credit healthInformation such as repayment history, credit accounts, credit utilisation, credit history and credit enquiries can provide additional context about the credit profile.
In simple terms, a credit score provides a number, while credit health provides a broader view of how credit has been managed.
Why does credit health matter?
Credit information can become relevant when an individual applies for a loan or credit card, manages existing credit or plans future borrowing.
Regularly reviewing credit information can help individuals remain aware of their credit position and identify information that may need attention.
What information helps understand credit health?
A credit report can provide information that helps individuals understand their credit profileThe exact information available can vary depending on the credit bureau and report.
|
|
|
|
|---|---|---|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
What is credit analysis?
Credit analysis is the process of reviewing credit-related information to understand an individual’s credit profile and creditworthiness.
Credit analysis can involve reviewing:
-
Credit score -
Repayment history -
Credit accounts -
Credit utilisation -
Credit history -
Credit enquiries
Looking at these factors together can provide more context than reviewing a credit score alone.
For example, a credit score can provide a quick indication of credit standing, while credit history and account information can provide additional insight into how credit has been managed.
Credit score vs credit health: what is the difference?
Credit score and credit health are related, but they are not the same.
|
|
|
|---|---|
|
|
|
|
|
|
|
|
|
|
|
|
In short: a credit score provides a numerical summary, while credit health provides a broader understanding of an individual’s credit profile.
Why should credit health be checked?
Checking credit information can help individuals stay informed about their current credit position.
|
|
|
|---|---|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
How does the Bajaj Finance Credit Pulse Report help?
The Bajaj Finance Credit Pulse Report provides an online route to check available credit informationIt can serve as a starting point for individuals who want to check their credit score and understand their credit position.
Rather than looking at a credit score in isolation, reviewing the available credit information can provide greater context about the credit profileA credit score is the starting pointReviewing available credit information provides greater context about the credit profile.
How to read credit information?
Checking a credit report is useful when the information can be understood in context.
|
|
|
|---|---|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
If any information appears incorrect or unfamiliar, it can be reviewed and, where necessary, raised with the relevant lender or credit bureau.
How can individuals maintain healthy credit?
Understanding credit health is only the first stepResponsible credit management can also help individuals maintain their credit profile.
-
Pay credit obligations on time: EMIs and credit card dues should be paid by their due dates. -
Monitor credit utilisation: Regularly reviewing credit card usage can help individuals remain aware of how much available revolving credit is being used. -
Avoid unnecessary credit applications: Individuals can avoid applying for credit when there is no immediate need for additional borrowing. -
Review credit information periodically: Periodic checks can help individuals remain aware of changes in their credit profile. -
Check for unfamiliar activity: Accounts or enquiries that appear unfamiliar should be reviewed and, where necessary, raised with the relevant lender or credit bureau.
When should a credit score be checked?
There is no single situation in which a credit score needs to be checkedIndividuals may consider reviewing their credit information at different points in their credit journey.
-
Before applying for a loan -
Before applying for a credit card -
When reviewing existing credit -
After closing a credit account -
When planning future borrowing -
When unfamiliar credit activity appears -
As part of regular financial planning
A periodic review can help individuals remain informed about their credit position instead of checking it only when a new credit application is being considered.
Stay informed about your credit profileCheck your credit score and credit report for free with the Bajaj Finance Credit Pulse Report.
*Terms and conditions apply.
About Bajaj Finance Limited
Bajaj Finance Ltd(BFL), a subsidiary of Bajaj Finserv Ltd., is a deposit-taking Non-Banking Financial Company (NBFC-D) registered with the Reserve Bank of India (RBI) and is classified as an NBFC-Investment and Credit Company (NBFC-ICC)BFL serves over 124.43 million customers through a diversified portfolio comprising consumer loans, SME finance, commercial lending, rural lending, fixed deposits and payments, offered through Web, App and at 4,000+ locationsAs a FinAI company, BFL is focused on continuous innovation through smart use of technology, data and analytics to drive seamless, simplified and personalized experiences for its customersBFL has the highest domestic credit rating of AAA/Stable for long-term borrowing, A1+ for short-term borrowing, and CRISIL AAA/Stable & [ICRA]AAA(Stable) for its FD programIt has a long-term issuer credit rating of BBB/Stable and a short-term rating of A-2 by S&P Global ratingsIt has been assigned a ‘Baa3 Corporate Family Rating’ with Stable outlook from Moody’s Rating.