IMA India’s October 2026 Business Confidence and Performance Index (BCPI) reveals a striking split in corporate sentimentBusiness leaders have become markedly more cautious about the economy, yet expectations for their own businesses and capital expenditure have improvedThe headline index fell 2.8 points to 57.3 from July’s 60.1, remaining above the neutral level of 50More than 150 CEOs and CFOs participated in the quarterly survey, which covers Q3 FY27.
The economy index dropped 16.8 points to 45.7, its sharpest fall since Q4 FY22Meanwhile, the business index rose from 60.2 to 62.1 and the capital expenditure index increased from 55.8 to 57.4The resulting 16.4-point gap between business and economic sentiment is the report’s central findingCompanies appear more confident about opportunities within their own operations than about the environment around them.
Economic caution contrasts with firmer business plans
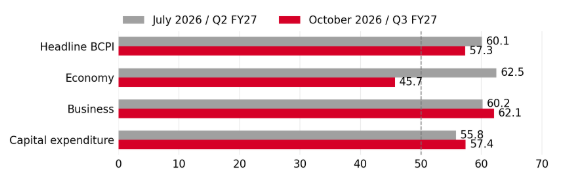 |
Index levels; 50 = neutralSource: IMA India, BCPI October 2026, page 3Redrawn from report data
That distinction matters when interpreting the headline declineTaken alone, it could suggest a broad retreat in corporate activityThe underlying responses paint a more discriminating pictureFirms continue to anticipate sales growth and commit to investment, even as their assessment of the economy has deterioratedThis suggests resilience in business plans, although expectations cannot guarantee subsequent performance.
The sales figures support this readingSome 51.3% of respondents expect sales to rise, against 9.7% expecting a declineFor new orders, the corresponding shares are 46.8% and 10.4%Profit expectations are also positive, with 37.0% anticipating an increase and 18.2% a fallNearly six in ten firms, 57.6%, have either signed off on or intend to make new investments, broadly unchanged from 57.1% in July.
Yet there is little expectation of a rapid improvement in the wider economyLooking ahead to January 2027, 49.4% anticipate unchanged conditions, 26.6% expect weakening and 24.0% expect strengtheningCorporate plans therefore appear to rest on opportunities firms can identify today, rather than a widely shared expectation that economic conditions will soon become more favourable.
The current assessment is already subduedOnly 16.8% of respondents said macroeconomic conditions had strengthened compared with three months earlier, while 34.2% reported weakening and 49.0% saw no changeThe difference between these assessments and the positive sales outlook helps explain why the headline index alone cannot capture the choices businesses are making.
Smaller firms expect better profits but remain cautious on investment
A second revealing split emerges by company sizeFirms with revenues below Rs 500 crore have the strongest profitability outlook, with a net score of 35.9, but a negative capital expenditure score of minus 8.8Companies above Rs 2,500 crore show almost the reverse pattern, with a profitability score of 5.3 and a capital expenditure score of 66.7Mid-sized firms record 5.8 and 20.0 respectively.
Net scores measure the percentage expecting an increase minus the percentage expecting a decreaseThey describe the balance of responses, not the rate at which profits or investment will growThe contrast suggests that improved profit expectations among smaller businesses are not yet translating into greater willingness to investAmong the largest firms, investment intentions remain strong despite a much narrower positive balance on profits.
Profit and investment expectations diverge by company size
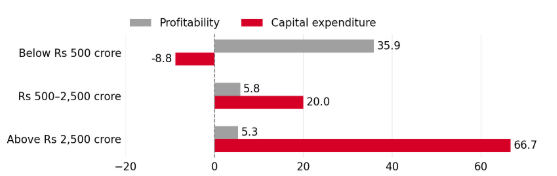 |
Q3 FY27 net scores, percentage points; revenue groups as reportedSource: IMA India, BCPI October 2026, page 13
This is an important qualification to the apparent resilience of capital spendingThe aggregate figures conceal markedly different appetites for investment across revenue groupsA broader investment upswing would require greater participation from smaller businessesThe survey does not establish why they are holding back, so the figures should not be treated as evidence of a particular financing constraint or cause.
Sectoral results reinforce the picture of uneven confidenceConsumer goods recorded a headline index of 47.2, down from 55.7 in July and below the neutral markConstruction and industrials improved to 61.1 and 60.4 respectivelyThe automotive index remained comparatively high at 64.9, despite declining from 68.5These differences suggest that demand and confidence are following distinct paths across industries.
Hiring offers another useful nuanceThe share expecting hiring to increase slipped from 28.6% to 27.0%, but the share expecting a decrease fell more sharply, from 27.3% to 17.1%The improved net balance therefore reflects fewer negative responses rather than a surge in recruitment appetiteTogether, the findings describe businesses that still see room to grow, while remaining selective about where they commit resources.
Spending priorities offer a further indication of selectivityThe share anticipating higher marketing expenditure rose to 30.7% from 15.8% in July, while 21.6% now expect a reductionTeam morale budgets remain under pressure, with 33.8% expecting lower spending and 16.2% expecting an increaseThe pattern suggests a preference for expenditure aimed at winning business, alongside continued restraint in other discretionary budgets.
About the survey
IMA India’s BCPI is a quarterly survey of CEOs and CFOsThis release draws on the October 2026 report, Bifurcating ExpectationsIndex readings use 50 as neutral; net scores use zeroSurvey responses reflect assessments and intentions, rather than measured changes in economy-wide output, employment or investment.